Go Program Way2Go Card

Screenshots
Details
- Rating
- 24.40K reviews
- Version
- 3.3.5
- Developer
- Conduent Incorporated
Analysis by Norviv
When I review a finance app, I pay less attention to polished wording and more attention to whether it helps me answer a simple question quickly: how much money can I actually use right now? Go Program Way2Go Card is built around that practical need. It is the companion app for the Way2Go Card, developed by Conduent Incorporated, and its main job is to put balance and transaction information in one place rather than turn everyday money management into a complicated budgeting project.
That narrow purpose is both its strength and its limitation. I found it most useful when I wanted a quick view of available funds, recent card activity, and basic account information connected to the card. I would not choose it as a replacement for a full-service bank app, a spending tracker, or an investment tool. It belongs to a more specific part of personal finance: helping cardholders keep an eye on money already loaded onto their Way2Go Card.
The app is free, rated for Everyone, and available for devices running at least OS version 10. It has been available since August 14, 2015, and the current version is 3.3.5. Its presence on the major mobile audience is clear, with over a million installs, while its average rating sits at about 3.5 from roughly 58 thousand ratings and 24 thousand written reviews. Those figures suggest a useful but uneven experience: many people rely on it, yet not everyone finds the app equally smooth or dependable.
What using Way2Go Card feels like in everyday life
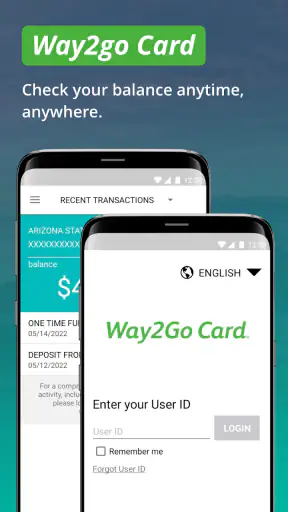
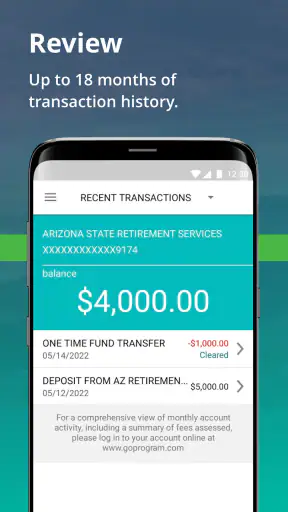
The first thing I noticed is that this is an account-checking tool, not a financial command center. The store summary focuses on monitoring an available balance and transaction activity, and that accurately describes the app’s role. I open it when I need confirmation before using the card, not when I want a detailed monthly plan or advice about how to improve my finances.
A realistic example is paying for groceries after work. Instead of guessing whether a previous purchase has already reduced the card balance, I can check the available amount and look at recent activity before reaching the checkout. That small step matters more with a prepaid or program-issued card, where an incorrect assumption about the remaining balance can cause an awkward declined payment. The app is valuable here because it supports a decision at the exact moment I need it.
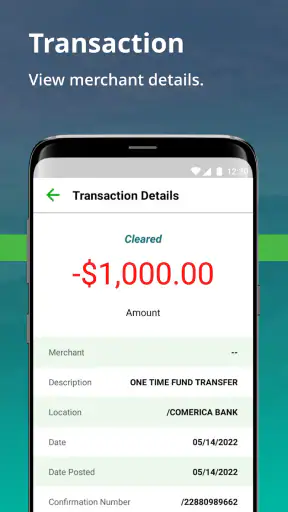
Another practical use is checking a transaction after using the card at a shop, restaurant, or online service. Looking at the activity can help me recognize whether the purchase appears in the account and whether the amount looks familiar. I still treat the transaction list as a record to review carefully rather than as a complete explanation of every payment issue. A pending or unfamiliar entry may require patience or a separate support conversation, so the app should not be mistaken for an instant dispute-resolution service.
I also see value in checking the account before planning a small purchase. That is different from maintaining a traditional bank account, where I might have several balances, automatic transfers, savings goals, and bill payments visible together. Way2Go Card keeps the focus on the card itself. For someone who only needs that focused view, the reduced scope can feel clearer than a crowded banking dashboard.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
A focused companion rather than a complete bank replacement
Compared with a standard bank app, the Way2Go Card experience is more limited by design. A bank application usually brings checking, savings, transfers, deposits, statements, and other services into one broad workspace. This app is better understood as a window into a particular card account. If your main question is “What is available on my Way2Go Card?” it is appropriately focused. If your question is “How do all my accounts fit together?” you will probably need another app as well.
That distinction is important before downloading it. I would recommend it to a cardholder who wants convenient mobile visibility and does not expect full banking functionality. I would skip it as a primary finance app if I needed category-based spending analysis, a unified view of several institutions, or tools for long-term financial planning. Installing it will not turn the Way2Go Card into a conventional checking account, and no interface can remove that underlying difference.
The free price also makes it easy to try without adding another subscription to a monthly budget. Still, “free” does not mean that every part of the experience will feel effortless. Registration, sign-in, security checks, or account recovery can be more important than the price when money is involved. I judge this kind of app by whether it lets me regain access and verify activity without unnecessary confusion, not simply by whether the download costs anything.
Trust begins with knowing what the app is for
For me, trust in a finance app starts with a clear boundary. Go Program Way2Go Card presents itself as a Way2Go Card companion, not as an independent wallet or a general-purpose banking platform. That clarity reduces one common risk: expecting the app to perform actions it was never meant to perform. I would use it to monitor the card, then look elsewhere for broader money management.
The developer is identified as Conduent Incorporated, which gives the app a recognizable product owner rather than leaving the service’s identity vague. That does not automatically guarantee a perfect experience, but it gives me a concrete name to associate with the application and its support responsibility. When I use a finance app, I want to know which service I am entering before I provide account credentials, and the Way2Go branding makes that connection relatively straightforward.
The app’s age rating of Everyone is useful context, but it should not be confused with a promise that every financial situation will be simple for every user. The rating describes audience suitability, while account access and card eligibility are separate practical questions. A parent, caregiver, or support worker helping someone use the app should still make sure the cardholder understands which details are sensitive and when not to share a screen.
Account controls deserve more attention than appearance
When I use a finance app, I look for the choices it gives me around access. The most important controls are not decorative screens; they are the ability to sign in deliberately, review the correct account, and avoid exposing information when someone else is holding the phone. I recommend treating the app as a private account tool even when the device is shared with family members.
A good personal routine is to check the card balance in a private setting, close the app when finished, and avoid saving account details in notes or screenshots. This is especially useful if the phone is used by children, coworkers, or anyone who may not understand the importance of card information. The app can show useful financial details, but that usefulness also means the screen deserves the same care as a bank statement.
I would also keep the application and the phone’s operating system maintained. The current version is 3.3.5, and the minimum operating-system requirement is version 10. Staying on a supported device environment is a sensible part of account hygiene. It does not guarantee that every login or display issue disappears, but it removes one avoidable source of friction when checking a balance or transaction.
One tip I found particularly sensible is to use the transaction view as a regular review habit rather than waiting until something goes wrong. A quick check after several purchases can make an unfamiliar amount easier to identify because the surrounding activity is still fresh in my memory. This is more useful than opening the app only after a declined payment, when I may already be stressed and unsure which purchase caused the problem.
Where sensitive moments can occur
The most sensitive moment is the sign-in itself. Any app connected to card activity deserves careful attention before credentials are entered. I avoid signing in over an untrusted public connection, and I do not let another person “help” by taking control of the phone unless I am comfortable with that person seeing account information. These are user habits rather than special app features, but they matter because the app’s purpose is to display financial details.
The next sensitive moment is interpreting the balance. An available balance is useful for deciding whether a purchase is affordable, but it is not the same thing as a complete financial picture. I would not use the displayed amount to estimate income, plan long-term bills, or assume that every recent card action has settled exactly as expected. For a larger purchase, I prefer checking the activity carefully and allowing for the possibility that a transaction may need time to appear or update.
Transaction review is also where user judgment matters most. If I see an amount I do not recognize, I first compare it with receipts, online orders, and recent travel or household spending. I would not immediately assume the app is wrong, but I would not ignore the entry either. The app helps me notice the issue; resolving an unauthorized or disputed transaction may involve the card program’s support process outside the screen.
Another data-sensitive situation occurs when sharing a screenshot. A balance and transaction list can reveal more than people realize, including spending patterns and identifying details. I would crop or avoid sharing such images entirely. This is one of the hidden trade-offs of convenient mobile access: the information is easier for me to reach, but it is also easier to expose accidentally if I treat the display as harmless.
How much control the user really has
The app’s strongest form of user agency is visibility. I can check the card’s current position and inspect activity without waiting to find a paper record or using a desktop browser. That makes it easier to make a deliberate purchase decision. In my experience, visibility is not a flashy feature, but it is the control that prevents avoidable surprises.
At the same time, visibility should not be confused with control over every underlying card process. Seeing a transaction does not necessarily mean I can change it, cancel it, or resolve it from the same screen. This is why I would keep receipts for important purchases and note the date, merchant, and amount when something appears questionable. Those details make a later support conversation more precise.
I also recommend deciding in advance what “normal activity” looks like for the card. For example, if the card is used for a limited set of household expenses, an unexpected merchant name deserves a closer look. If several people are authorized to use the card, the review process becomes more complicated, and the app cannot replace an agreed household record. The practical advantage comes from combining the app’s activity view with a simple personal system.
For a user who has trouble remembering passwords or navigating account recovery, the app may feel less welcoming than its basic purpose suggests. Finance tools have to protect access, so some friction is understandable, but difficult recovery can become a serious barrier when the only reason for opening the app is to check an urgent balance. I would make sure the account’s recovery details are current and stored safely before an emergency purchase arises.
Who will benefit most, and who should choose something else
I think the best match is someone who already uses a Way2Go Card and wants a mobile way to monitor it. The app is especially practical for people who make frequent small purchases and want to confirm the remaining amount without maintaining a separate handwritten ledger. It can also help a caregiver or family member support routine checking, provided the cardholder’s privacy and account ownership remain respected.
It is less suitable for someone searching for a full budgeting solution. If I wanted automatic categories, charts showing spending trends, several connected accounts, savings targets, or bill-management tools, I would look at a broader personal-finance application. Those tools answer different questions. Way2Go Card is about the state of one card account, not a complete plan for managing every part of my money.
I would also hesitate to rely on it alone if my financial routine depends on detailed records for taxes, reimbursement, or business expenses. The transaction view may help me remember activity, but serious recordkeeping often requires exporting, filing, or reconciling information in a more deliberate system. The app can be one reference point without being the only archive.
People who rarely use the card may not gain much from installing it. If the card is used only occasionally and the balance is easy to verify another way, the extra sign-in may not justify itself. The real benefit appears when mobile visibility changes behavior: checking before spending, reviewing activity soon after purchases, and noticing questionable entries promptly.
My cautious verdict after weighing convenience and friction
Go Program Way2Go Card succeeds when I use it for its actual job. It gives Way2Go Card users a direct mobile view of available funds and transaction activity, and that can make everyday spending less uncertain. The free download, Everyone rating, and broad install base make it approachable, while the 3.5 average rating reminds me to keep expectations realistic rather than assume every user will find the experience flawless.
I would recommend it to a friend who holds a Way2Go Card and wants a convenient monitoring tool. My advice would be to build a small routine around it: check the balance before an important purchase, review new activity while the details are still familiar, protect the screen from casual viewing, and keep receipts for anything that may need follow-up. Those habits turn a simple account viewer into a more useful part of daily money management.
I would not recommend treating it as a replacement for a bank app, a budgeting platform, or a support channel for every card problem. Its value comes from focus, and its limits come from that same focus. The best reason to use it is informed checking, not the expectation of complete financial control. If that matches what you need from a Way2Go Card companion, it is worth trying. If you want a broader picture of your finances, pair it with a separate tool designed for that wider job.
Overall, my opinion is cautiously positive. The app addresses a specific and useful need, and the developer’s clear association with the Way2Go Card gives the service a defined identity. I appreciate the practical access to balance and activity, but I would keep my own security habits and records in place. Used with those boundaries, it can reduce uncertainty around ordinary card purchases without pretending to be more than a focused finance companion.
Frequently Asked Questions
01What is the Go Program Way2Go Card app used for?
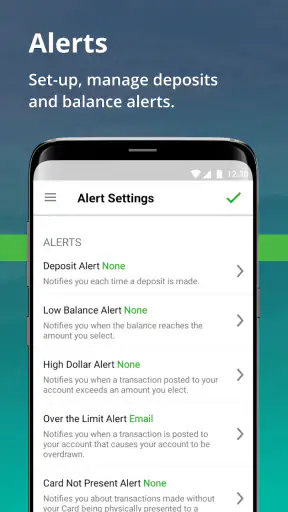
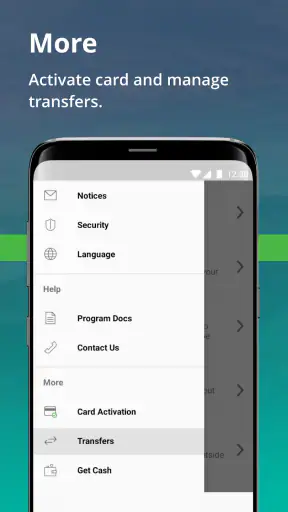
The Go Program Way2Go Card app is designed for people who receive government benefits through a Way2Go Card. After signing in, users can generally check their available balance, review recent transactions, view payment information, locate participating ATMs, and manage certain card settings. The exact features can vary depending on the state or program that issued your card, so the app should be used alongside official program instructions.
02How do I register or sign in to the Go Program Way2Go Card app?
To use the app, you typically need an active Way2Go Card account and the personal information requested during registration, such as your card details and identifying information. Follow the on-screen enrollment process carefully and create a secure username, password, or PIN where required. If registration fails, your card is not activated, or your information is rejected, contact the customer service number printed on the back of the card.
03Can I check my balance and transaction history with the app?
Yes, checking your balance and reviewing recent card activity are among the main reasons users install the Go Program Way2Go Card app. The displayed balance may not immediately reflect every transaction, especially when a purchase is pending or a merchant has placed a temporary authorization hold. Always compare the app’s information with official account notices and report unfamiliar transactions promptly.
04Does the Go Program Way2Go Card app help me find ATMs and avoid fees?
The app may provide tools for locating ATMs or identifying places where your Way2Go Card can be used, depending on the features enabled for your issuing program. ATM availability, withdrawal limits, surcharges, and fee-free networks can differ by state and card agreement. Before withdrawing cash, review the fee information in the app or cardholder terms so you understand any possible charges.
05What should I do if my Way2Go Card is lost, stolen, blocked, or used without permission?
If your card is lost, stolen, damaged, blocked, or showing transactions you do not recognize, act quickly rather than waiting for the app to update. Use the available card-management options if supported, then contact the official Way2Go customer service number printed on your card or provided by your state program. Never share your password, PIN, full card number, or verification codes with strangers.


